Starting a business usually begins with an idea and a lot of optimism. You see an opportunity, recognize something you can do differently, or decide it is finally time to build something of your own. That excitement matters, but before you invest heavily in equipment, sign contracts, hire employees, lease a building, or start taking customers, there is another side of the business that deserves just as much attention: risk.
I have talked with business owners over the years who had great ideas but did not fully understand the financial, operational, legal, or insurance risks that came with them. Sometimes those risks can be managed fairly easily. Other times, one detail about the operation completely changes the conversation.
That does not mean you should be afraid to start a business. It means you should understand what you are getting into before you get too far into it.
At The Koch Insurance Group, we believe some of the most valuable insurance conversations happen before a business ever opens its doors. If we understand what you are planning to do, we can ask questions, identify potential exposures, and help you understand what may need to be addressed before you start investing your time and money.
A Good Business Idea Still Needs a Good Business Plan
One of the first risks every new business owner should consider has nothing to do with insurance. You need to know whether the business itself makes financial sense.
Do people actually want what you are offering? What will it cost to operate? How long can you continue if revenue takes longer than expected? Who are your competitors? What makes your business different? How much money do you need before you open?
Market research can help determine demand, market size, competition, location considerations, and pricing before a business launches. The U.S. Small Business Administration specifically recommends researching these areas because doing so can help entrepreneurs reduce risk while an idea is still being developed.
Cash flow deserves the same attention. A business can have customers and still struggle if there is not enough money available to cover payroll, rent, inventory, equipment, insurance, and other operating expenses. Startup costs should therefore be calculated before launch, including expenses such as licenses, permits, insurance, salaries, equipment, professional services, marketing, and inventory.
Insurance can protect against certain risks, but it cannot fix a business model that does not work. Understanding the financial side of the business needs to happen alongside understanding the insurance side.
Understand Your Liability Before You Open
Liability is where many new business owners underestimate their exposure.
What happens if someone gets hurt because of your operations? What if you damage a customer’s property? What if an employee causes an accident while working? What if a client claims your professional advice caused them financial harm?
The answers depend heavily on what your business actually does.
Consider the difference between opening a marketing agency and starting an electrical contracting company. Both are businesses, but the potential losses associated with their operations are very different. The marketing agency may have significant professional liability or cyber exposure, while an electrical contractor may have substantial property damage, bodily injury, vehicle, employee, and completed-operations exposures.
This is one reason General Liability Insurance for a new business should never be treated as a universal solution. The SBA identifies several different forms of business insurance, including general liability, professional liability, commercial property, product liability, and Business Owners Policies, because different businesses face different types of losses.
Before purchasing coverage, we want to understand what could realistically go wrong and what the financial consequences could be.
Is Your Business Idea Actually Insurable?
This is a question I wish more entrepreneurs asked before opening.
A business can be legal. It can have customers. It can have a great concept. It can even have strong revenue potential.
That does not automatically mean the operation will be easy or affordable to insure.
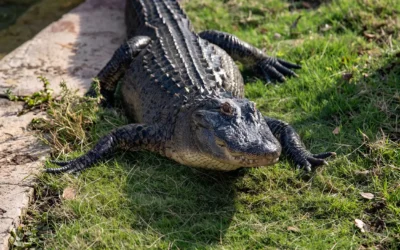
We get calls about unusual businesses and unusual risks fairly regularly. One example involved a mobile petting zoo whose main attraction was going to be a roughly 12-foot alligator.
We were able to find coverage for the operation, but there was an important problem: the policy contained an animal bite exclusion. Certain liability exposures could be covered, but an injury involving the animal created a very different situation.
That is an extreme example, but it demonstrates something every entrepreneur should understand.
Having business insurance does not necessarily mean every risk in your business is insured.
Sometimes coverage is available with exclusions. Sometimes only certain insurance markets will consider an operation. Sometimes coverage technically exists, but the premium required to transfer the risk is too expensive for the business model to support.
This is why talking with an experienced commercial insurance advisor before starting a business can be valuable. You want to understand those issues before spending heavily on an idea, not after everything has already been built.
Know What Your Insurance Does and Does Not Cover
New business owners sometimes approach insurance as another item on the startup checklist. They need General Liability Insurance, so they buy General Liability Insurance. They need a Certificate of Insurance, so they obtain one.
The problem is that the name of the policy does not tell you everything about the protection inside it.
Policies have limits, deductibles, conditions, endorsements, and exclusions. Different policies can address different risks, and coverage should be evaluated based on the operation rather than simply the policy name.
The SBA recommends assessing the accidents, natural disasters, lawsuits, and other events that could affect a company before choosing insurance. It also recommends comparing not only prices but policy terms and benefits.
That is good advice for any business owner, but especially someone purchasing small business insurance for the first time.
Do not be afraid to ask what is excluded. Ask what happens in the situations you are most concerned about. Ask whether your employees, vehicles, equipment, property, professional services, and other significant exposures have been considered.
Never just assume you are covered.
Your Business Structure Matters, But It Is Not Business Insurance
Choosing a business structure is another important decision entrepreneurs need to make before opening.
A sole proprietorship, LLC, partnership, and corporation can have different implications for taxation, registration, fundraising, paperwork, and personal liability. The SBA notes that business structure affects personal liability and recommends choosing carefully, with professional legal and accounting guidance where appropriate.
However, forming an LLC does not mean you no longer need business insurance.
Your business structure and your commercial insurance serve different purposes. New owners should talk with the appropriate attorney or accountant about business formation and with an insurance professional about transferring insurable risks.
This is also why building the right professional team early can make such a difference. Your accountant, attorney, banker, and insurance advisor should each be helping you understand a different part of the business.
Separate Your Business and Personal Finances
Once you begin accepting or spending money as a business, keeping business finances organized becomes important.
The SBA recommends opening a business bank account when a company is ready to begin accepting or spending money and notes that separating business funds from personal funds can provide financial and legal benefits.
From an insurance perspective, this also reinforces an important principle: treat the business like a business.
Know what assets belong to the company. Know what vehicles are being used for business. Know who is working for you. Keep contracts and records organized. Document major equipment purchases. Understand where business property is located.
Good business practices make risk easier to identify and manage.
Do Not Forget Licenses, Permits, Contracts, and Regulations
Insurance is only one part of protecting a new business.
Depending on what you do and where you operate, there may be federal, state, county, or municipal requirements involving licenses, permits, taxes, zoning, employment practices, professional licensing, or other regulations.
Your location can also determine which taxes, zoning laws, and regulations apply to your business. The SBA recommends evaluating these requirements when choosing where to establish an operation.
Contracts create another layer of risk.
A customer, landlord, general contractor, property manager, or other organization may require specific insurance before allowing you to work. Those requirements could include General Liability, Workers’ Compensation, Commercial Auto, Professional Liability, Umbrella coverage, Additional Insured endorsements, Waivers of Subrogation, or specific liability limits.
Do not wait until the morning a project begins to discover that your existing policy does not satisfy the contract.
Have someone review the requirements early.
Cyber Risk Is Not Just a Big-Business Problem
New businesses are often digital businesses whether they realize it or not. You may accept credit cards, store customer information, use cloud-based accounting software, send invoices electronically, maintain employee records, or rely heavily on email.
That creates another category of exposure.
Cyber risks can include phishing, ransomware, compromised credentials, data breaches, fraudulent payments, and other technology-related incidents. Risk-management guidance for entrepreneurs increasingly treats technology risk as a core startup concern because virtually every modern business relies on digital systems in some way.
Whether Cyber Liability Insurance belongs in your insurance program depends on your operation, but cybersecurity itself should be part of the conversation from the beginning.
Business Insurance Should Be Part of Your Startup Budget
Insurance should not be something you price after every other startup decision has already been made.
Include it in the budget early.
The cost of business insurance for a startup can vary significantly depending on your industry, operations, employees, location, property, vehicles, claims exposure, limits, and the types of coverage needed.
For some businesses, insurance is relatively straightforward. For others, it can become one of the more significant operating expenses.
Knowing that before you open allows you to build a more realistic business plan.
If the insurance required to operate your idea responsibly makes the business financially impossible, you need to know that before investing heavily. Sometimes we can restructure the insurance. Sometimes the operation itself can be changed. Other times, the numbers simply do not make sense.
Those may not always be easy conversations, but they are much better conversations to have early.
Build a Business That Can Grow
The insurance conversation does not end when you open your doors.
The SBA recommends reassessing business insurance annually because growth can increase liabilities and changes such as new equipment or expanded operations may affect coverage needs.
The business you insure in year one may look completely different in year three.
You may hire employees, purchase vehicles, add services, move into a commercial building, acquire expensive equipment, start using subcontractors, land larger contracts, or begin working in other states.
Those are signs of growth, but they can also introduce new risks.
Your insurance should continue to reflect the business you actually operate.
Questions to Ask Before Starting Your Business
Before opening, take the time to answer a few important questions:
- Is there enough demand for what I am offering?
- Do I understand my startup and ongoing operating costs?
- What could realistically cause a serious financial loss?
- Could a customer, employee, or third party be injured because of my operations?
- Will employees or owners drive for the business?
- What property, tools, inventory, or equipment needs protection?
- Will I collect or store sensitive customer information?
- What insurance will my customers or contracts require?
- Are there licenses, permits, or regulations I need to satisfy?
- Is my business operation actually insurable at a price the company can afford?
- What does my insurance exclude?
- Who can I call when I do not understand something?
You do not need to know every answer yourself. That is why you build a team of professionals around your business.
Start With the Right Questions
Starting a business always involves some level of risk. You cannot eliminate every possibility of something going wrong, and insurance cannot protect you from every business challenge.
What you can do is understand those risks before you open.
Research the market. Know your numbers. Choose the appropriate business structure with qualified legal and tax guidance. Understand your contracts and regulatory responsibilities. Protect your digital systems. Identify the losses your company could not comfortably absorb on its own, and have an honest conversation about what insurance can and cannot do.
At The Koch Insurance Group, we work with small to mid-sized businesses throughout Spring, The Woodlands, Conroe, Magnolia, Tomball, Montgomery County, Houston, and across Texas. Our approach is to understand how the business actually operates, identify potential gaps, review contracts and exposures, and help owners make informed decisions about their commercial insurance.
If you are preparing to start a business and have questions about business insurance in Texas, General Liability Insurance, Commercial Property Insurance, Commercial Auto, Professional Liability, Workers’ Compensation, contract requirements, or unusual business risks, contact The Koch Insurance Group before you open. Sometimes a conversation early in the process can uncover something you had not considered and give you the information you need to move forward with a better plan.
You have enough to think about when building a business. Your insurance should not be something you simply hope is right.
Understand the risk. Ask the questions. Then make an informed decision.